QR Ph
. Brief
Bringing the national QR standard into PayMongo, so anyone with any bank or e‑wallet could pay a small business by scanning one code.
- Role
- Product design, UI/UX, data-driven design
- Team
- 1 product designer, 1 UI designer, 3 engineers, 2 QA, 1 PM
- Timeline
- Oct 2023 — Jan 2024
- Methods
- Desk research, survey, journey mapping, design specs
. Outcomes
- ₱1.105B+
- Total payment volume through QR Ph
- 8,000
- Merchants configured
- #3
- Top-grossing payment method on PayMongo
. The problem
Digital payments weren’t reaching everyone.
Small businesses and unbanked customers were left out of digital payments, and checkout had too much friction.
QR Ph was new, so trust was low. We also had little time and real limits from partner banks.
. What research said
Demand was there. Trust wasn’t.
- 01Usage was climbing fast.QR Ph grew 177% year on year to ₱32.7B in Q1 2023, backed by the BSP.
- 02Awareness lagged.Many people didn’t know it existed, or didn’t trust it yet.
- 03Tech got in the way.Slow internet and glitches broke the moment of payment.
- 04People wanted three things.Speed, convenience and security — and proof of all three.
↳ The gap between usage and awareness was the brief. Everything after this is about closing it.
. How I worked
- 01ResearchDesk research and a user survey.2—3 days
- 02Map pain pointsA hypothesis-first journey map to find where people stall.3—5 days
- 03Align the teamKick-offs, MVP reviews for feedback and compliance, design guides and specs.3—5 days
- 04DesignUser-centred concepts, refined with the team.5—7 days
. Key decisions
Make the unfamiliar feel safe.
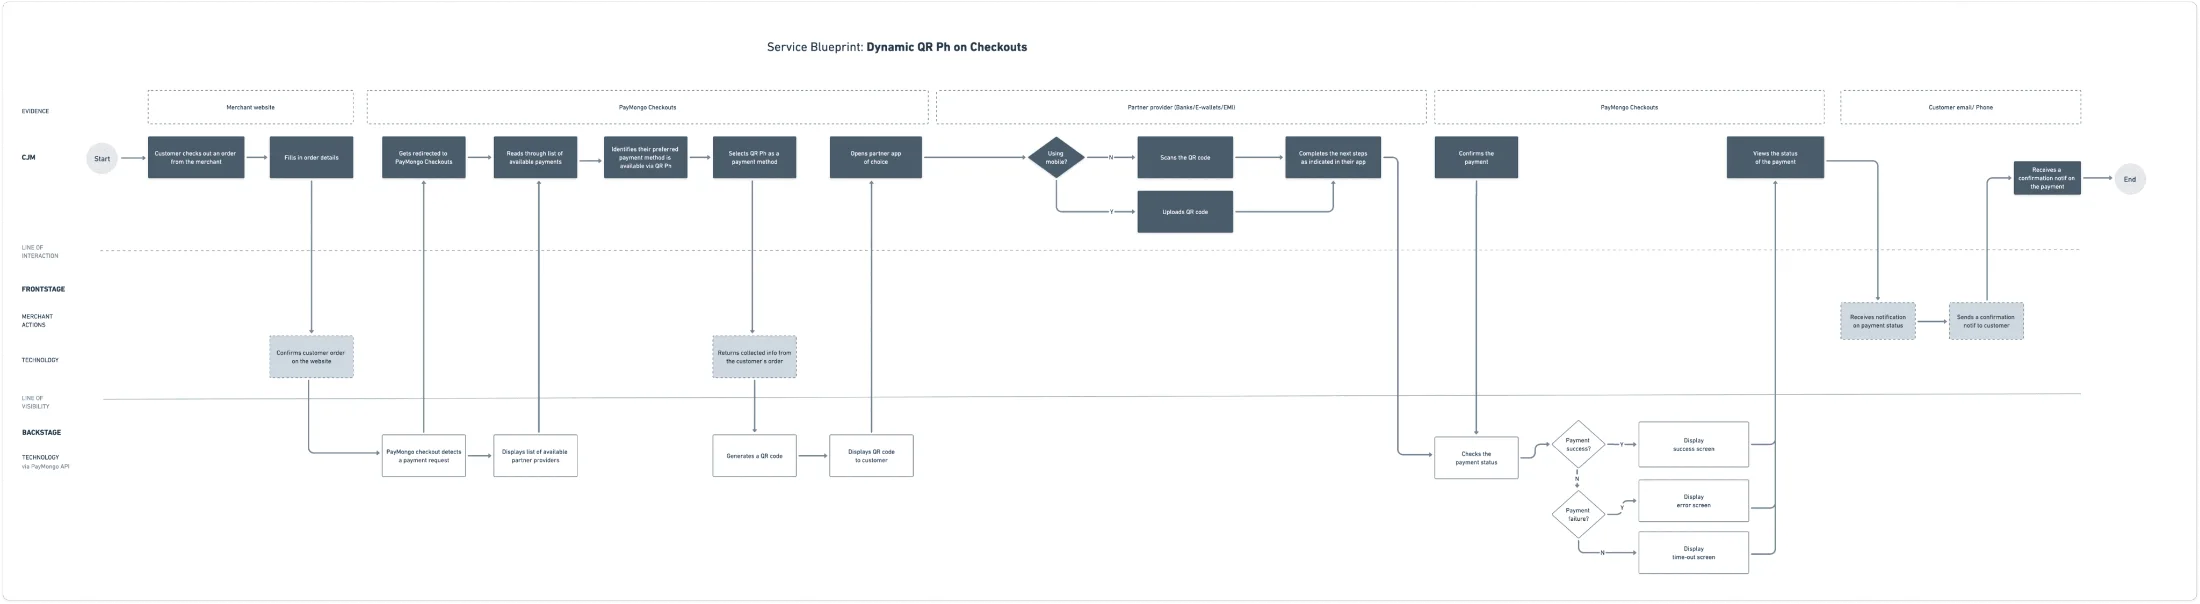
- 01Show the banks up front.Customers see right away that their own bank or e‑wallet works.
- 02Call it “Scan to Pay”.A plain label beats a brand name people don’t know yet.
- 03Name the partners on the QR screen.With a full list one tap away.
- 04Be honest about limits.Partner rules meant codes expire, so the expiry and the waiting state are always visible.
- 05Set expectations in context.Small reminders tell people what happens next.
↳ None of these is a visual decision. They are all answers to “will this work with my bank, and what happens next?”
. Next
Case study 02
Loans that fit how small businesses actually earn. ↗